Lawsuit Protection

Organize ownership and separate risk before a claim places multiple parts of your financial life in jeopardy.

Start the Process
Successful couple in a private study discussing how to protect what they have built

Lawsuit Protection Overview

Lawsuit protection is the process of organizing assets, ownership, operations, and legal entities so that a problem involving one person, business, or property does not automatically expose everything else.

The objective is not to hide assets or avoid valid obligations. It is to establish a lawful structure before a dispute arises, maintain proper records, use appropriate insurance, and clearly separate activities that create risk from assets a family wants to preserve.

Understanding Lawsuit Exposure

Professionals and business owners can be drawn into claims through their own conduct, employees, partners, vehicles, properties, contracts, or professional services. Even a claim with little merit can create defense costs, lost time, privacy concerns, and settlement pressure.

Attorneys may evaluate available insurance and reachable assets when deciding how aggressively to pursue a case. Planning before a dispute gives the legal team more options than attempting to restructure ownership after litigation is threatened.

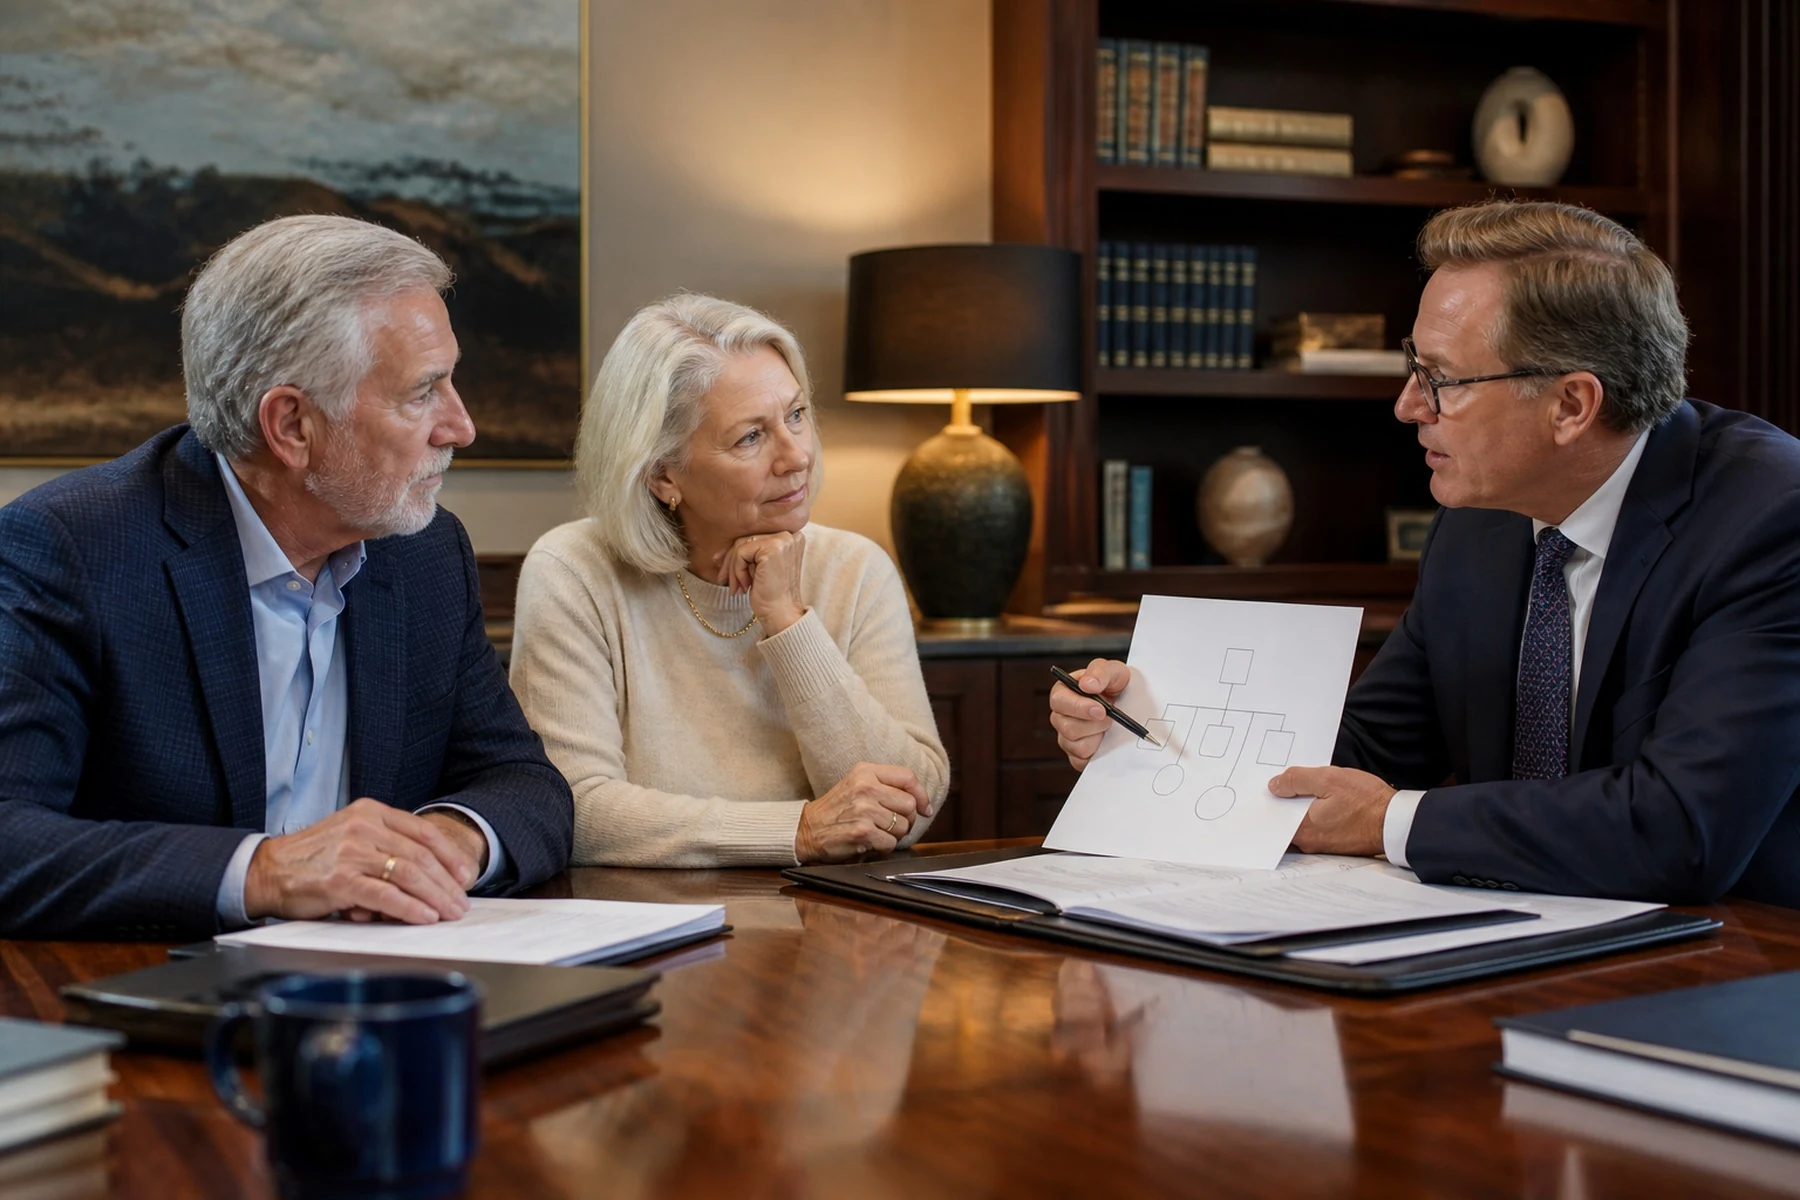
Attorney explaining a legal ownership structure to a mature couple

The Right Legal Structure

A sole proprietorship creates no legal boundary between the owner and the business. A corporation or LLC may separate business obligations from personal ownership, but assets held inside the operating entity can still be exposed to claims against that entity.

A customized plan may therefore use operating companies, property entities, holding entities, and estate-planning structures. The right arrangement depends on activity, ownership, jurisdiction, tax classification, and the assets involved.

Separating Risk

Assets that create liability should not automatically share the same ownership structure as assets that primarily hold value. An active business, rental property, vehicle, or commercial building can generate a claim. Cash, securities, artwork, and other passive assets usually present a different risk profile.

A Blueprint may separate operations, real estate, equipment, intellectual property, and financial assets into different ownership groups. Multiple properties or locations do not automatically require one entity each; value, equity, financing, partners, state law, cost, and attorney judgment all affect the recommendation.

Protecting Your Home

State homestead laws may protect some or all of the equity in a primary residence, but the rules vary significantly by jurisdiction and generally do not apply in the same way to vacation homes or investment property.

Existing title, mortgage terms, marital ownership, estate planning, tax consequences, and insurance must be considered together. The Blueprint identifies how the residence is currently owned and flags the alternatives for attorney review.

Entity Structures

Family limited partnerships, limited liability companies, and professional limited liability companies can organize ownership, management, and asset placement, but they are not interchangeable products.

Family Limited Partnership

A Family Limited Partnership generally has one or more general partners responsible for management and limited partners who hold economic interests without the same management authority. FLPs have historically been used for centralized management, family ownership, succession planning, and ownership transfers.
Limited Liability Company

An LLC can serve as an operating company, property owner, holding company, or investment entity. It offers flexible ownership and management terms and may use several federal tax classifications. Its governing documents and maintenance must support its intended purpose.

Professional Limited Liability Company

Some states allow licensed professionals to operate through a PLLC, while others require a professional corporation or another licensed entity. A PLLC generally does not eliminate personal responsibility for the owner’s own professional services.

Planning for Different People and Different Assets

Business owner in an active warehouse and logistics operation

Business Owners

Owners must coordinate the operating business, valuable assets, real estate, employees, partners, taxes, and succession. The Blueprint begins with how the business actually operates.

Experienced healthcare professional in a modern practice

Healthcare Professionals

Licensed professionals face professional liability, employee risk, practice ownership, equipment, office property, tax, and licensing concerns. State law may restrict the entity the practice can use.

Real estate investor outside a modern commercial property

Real Estate Investors

Real estate planning may involve residences, rentals, commercial property, land, development projects, mortgages, partners, and property management. Each property’s facts matter.

Senior executive in a refined corporate office

Executives & Professionals

Executives may have equity compensation, concentrated investments, deferred compensation, retirement plans, board roles, side businesses, and significant personal assets.

Retired couple relaxing together at home

Families & Retirees

Families and retirees often focus on preserving a residence, financial accounts, business interests, insurance, retirement assets, and a legacy for children or grandchildren.

Charging Orders

A charging order is a creditor remedy that may apply when a judgment debtor owns an interest in certain LLCs or partnerships.

Depending on the jurisdiction and entity, it may allow a creditor to reach distributions associated with the ownership interest without directly taking control of the underlying entity assets. The scope and exclusivity of this remedy vary by state, entity type, ownership structure, and current law. Any state recommendation must therefore come from the legal team, not from a generalized website rule.